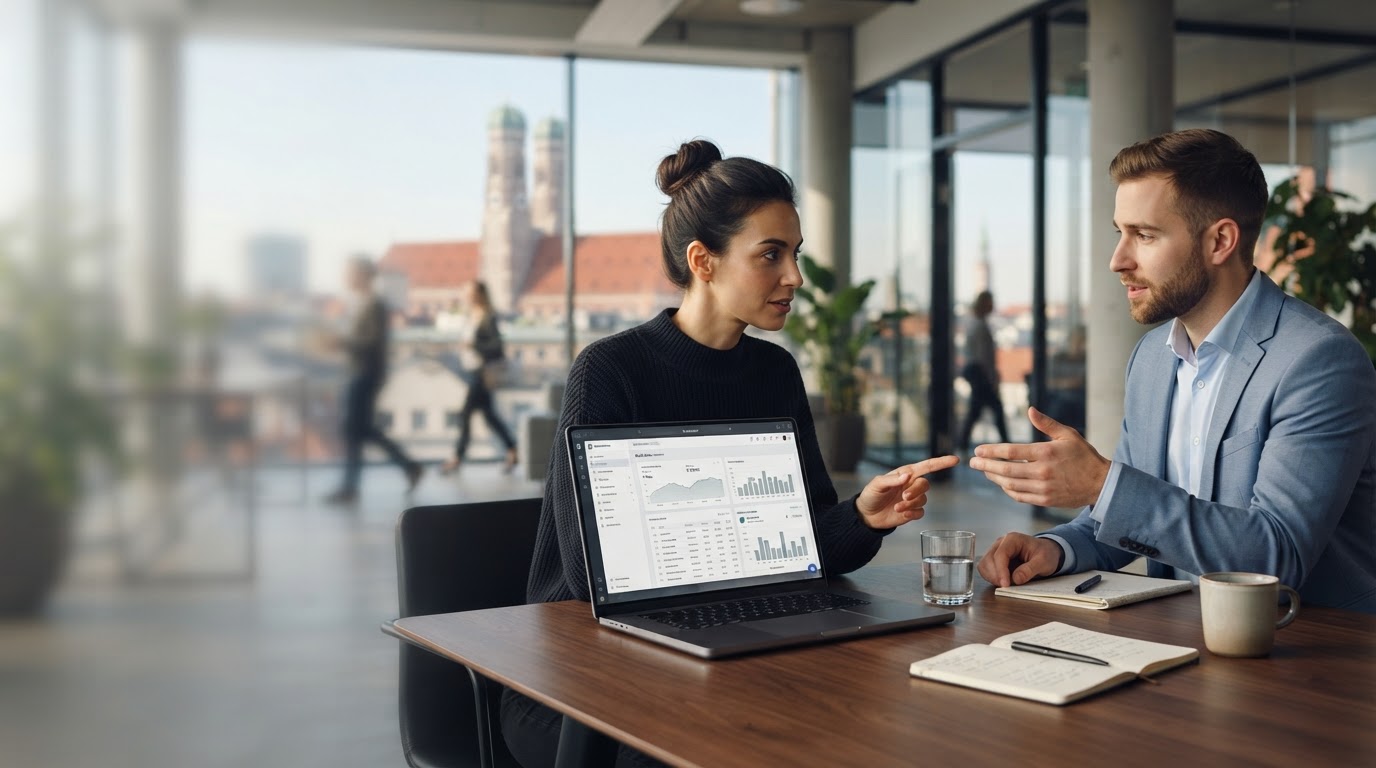
Lanca Capitorio applies predictive analytics to large, continuously updated data sets, surfacing passive income opportunities that are normally reserved for institutional research desks. No coding and no finance degree required to read the output.
The dashboard condenses thousands of data points per asset into a single, ranked recommendation, supported by the historical backtest behind it.
Private investors face the same volume of information as professional analysts, but without the tools to process it.
Our predictive modeling layer ingests market, fundamental, and macroeconomic data continuously, then translates the output into a plain-language recommendation. The underlying math stays complex; the result you see does not.
Each pillar addresses a distinct risk in passive income investing: staleness, exposure, and unverified assumptions.
Price feeds, earnings releases, and macroeconomic indicators are processed as they arrive, so recommendations reflect current conditions rather than last week's close.
The engine weighs expected yield against volatility and drawdown history, favoring risk-adjusted returns over headline percentages that look attractive but carry hidden exposure.
Every strategy is run against historical market cycles before it reaches your dashboard. This matters because passive income only stays passive if the underlying approach has survived a downturn.
We describe each stage openly. Understanding the process is part of trusting the result.
Structured and unstructured sources, including filings, pricing data, and economic releases, are collected and normalized into a common format.
Statistical models compare current conditions against decades of historical market behavior to identify recurring, measurable patterns.
The analysis is distilled into a scalable recommendation, a straightforward signal with the supporting evidence attached, so you can decide with context rather than blind faith.
The same engine adapts its weighting depending on the profile you select, including considerations relevant to the German market.
The model favors dividend-paying DAX constituents and investment-grade bonds, screening for consistent payout history rather than short-term spikes. ESG scoring is applied as an additional filter, reflecting the preferences of many German retail investors, and backtests emphasize drawdown limitation over maximum yield.
Here the engine widens its universe to include higher-volatility mid-cap equities and selected derivatives-based income strategies. Risk-adjusted return thresholds are relaxed in exchange for higher projected yield, but every suggestion still carries its full backtested drawdown history so the trade-off is visible, not hidden.
This profile pairs long and short positions to reduce correlation with broad index movements such as the DAX. It suits investors who want income less dependent on overall market direction, at the cost of a typically lower absolute return ceiling, which the dashboard states explicitly.
Direct answers to the questions we hear most often from new users in Germany.
Account and portfolio data are encrypted in transit and at rest, and access is restricted to the systems required to generate your recommendations. We follow data protection standards consistent with GDPR requirements applicable to users based in Germany and the wider EU.
The platform aggregates licensed market data feeds, public regulatory filings, and macroeconomic releases from established providers. Each data source is documented within the dashboard alongside the recommendation it informed.
No. The interface presents a ranked recommendation with a short, plain-language explanation. The statistical and modeling work happens behind the scenes; you review conclusions, not raw code or spreadsheets.
Start with a single asset class or run a full portfolio review. Either way, you receive the same backtested reasoning behind each recommendation.